The number of petrol stations (PS) for sale in Russia is increasing. This trend applies not only to individual independent PS not owned by major oil companies but also to networks that are "offloading ballast" - shedding their least profitable assets.
The number of listings for the sale of PS on various trading platforms and oil company websites has surged by 5.5 times over the past five years. However, the existence of a listing does not guarantee a sale; rather, it indicates that owners are seeking to divest themselves of their businesses.Typically, there are two reasons for such a move: the desire to profit from selling a promising business or, conversely, the intention to rid oneself of a loss-making enterprise. In the latter scenario, if the asset fails to sell, there is a high probability it will be closed down. This has implications for fuel supply, particularly in regions where there are no large networked PS. Moreover, the reduction in the number of players inevitably leads to diminished competition, which, if not resulting in price hikes, maintains prices at elevated levels.
Not only individual petrol stations are being sold, but entire regional networks as well.The number of PS began to decline as early as 2025. According to "OMT-Consult", it fell by 1.6%. This downward trend continued in the first half of this year, with a further decline of 1%. Notably, mobile refueling stations (container-based) have significantly diminished.
By the second half of 2026, there were approximately 28,000 refueling stations in Russia, just over 23,400 of which were traditional PS (selling gasoline and diesel, non-mobile stations).
The share of independent players in the total number of stations is around 65%. They are predominantly located in the east and south of Russia. However, in terms of gasoline and diesel sales, independents account for only 30% of the market. Primarily, the fuel for their stations is purchased through small wholesale, which is the segment that experienced the most significant price increase this summer and faced supply disruptions. This may explain the owners' inclination to sell their businesses, although the process also involves large players.
For instance, last week, operational PS, land parcels for business along federal highways, and production facilities of "Bashneft-Retail" were put up for sale or lease. The geographic distribution of these assets includes Sverdlovsk, Chelyabinsk, Kurgan, Orenburg, Samara, Ulyanovsk, Penza, Vladimir, Moscow, Ryazan, and Smolensk regions, as well as the Republics of Tatarstan, Mordovia, Udmurtia, Chuvashia, and Mari El. Previously, it was reported that "Gazprom" and "Lukoil" were selling their "non-core" PS. Lukoil’s website still lists eight PS for sale.
Regarding independent players, all eyes are on the troubles faced by one of the largest independent PS networks, "Trassa", which is grappling with a debt crisis and may be subject to external management or up for auction. Currently, approximately 170 PS are for sale across various trading platforms.
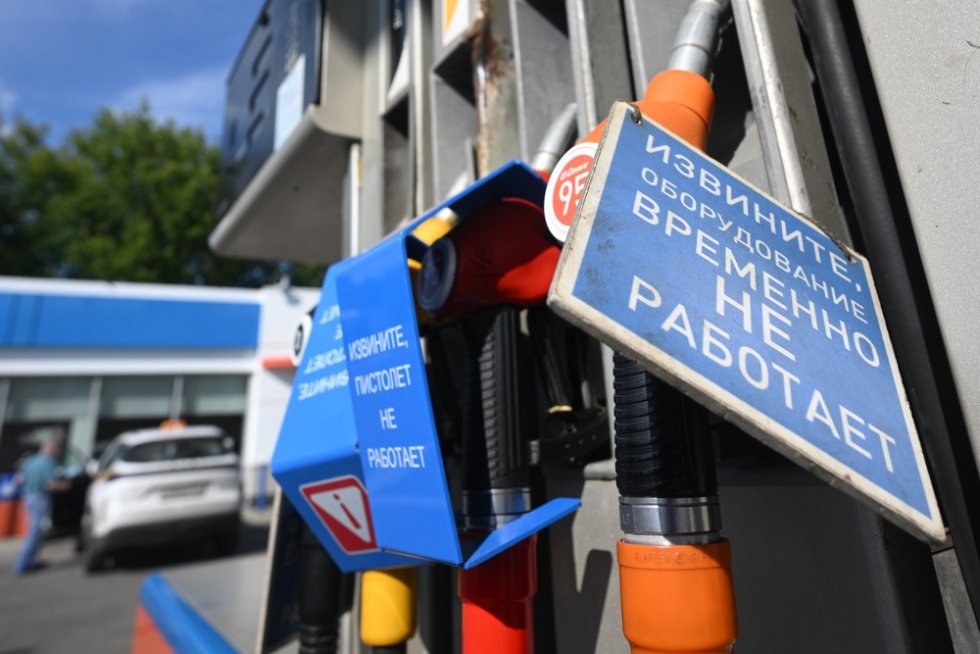
However, as noted by Yuri Stankevich, Deputy Chairman of the State Duma Committee on Energy, it is somewhat inappropriate to speak of a "mass sell-off." Today, the fuel retail sector represents a heterogeneous competitive landscape, with variations in different regions of the country. The fuel shortage has primarily impacted independent PS, many of which have today "pulled their hoses", thus contributing to the perception of an oversaturated market with assets that, de facto, find no application.
The geography of PS sale listings spans nearly the entire country. According to Sergey Tereshkin, CEO of Open Oil Market, the situation is attributed to reduced profitability of PS operations and issues with fuel accessibility for trade. Exchange prices for gasoline and diesel have risen by 30-37%, even higher in the small wholesale segment, resulting in fuel retail being in a more difficult position than the oil refining segment, which is subsidized.
Additionally, the reduced availability of fuel on the exchange has been exacerbated by diminished quotas for mandatory sales by major oil companies. The lower the quota and the more significant the leniencies regarding over-the-counter transactions, the less fuel is available to traders. Ultimately, the independent PS bear the brunt of these losses, sourcing gasoline and diesel from traders. A decline in the physical sales volume means that PS operators earn less on each litre of fuel sold.
According to Sergey Frolov, Managing Partner at NEFT Research, the redistribution of ownership in the retail fuel market under current conditions was anticipated. Currently, private owners of individual stations or small, inefficient networks are exiting the business. Large oil companies are also optimizing unprofitable locations and restructuring their networks to adapt to new conditions.
The expert believes that the reduction in the number of PS is unlikely to have a significant impact on the overall situation in the fuel sector, as many of them were already standing idle. With improvements in fuel supply conditions, the number of private PS is expected to rise again, particularly if high prices persist.
It is hardly feasible to sell PS now; this should have been done two years ago when the business was profitable, argues Dmitry Gusev, Deputy Chairman of the Supervisory Board of the "Reliable Partner" association and member of the expert council for the "PS of Russia" competition. However, the issue is not about trying to sell them but rather about our uncertainty regarding the necessity of these stations. Meanwhile, priorities for the domestic fuel market have now been established. The primary task is to ensure fuel supply for the networked stations of major companies, agricultural producers, and industrial enterprises, but not for independent PS networks, clarifies the expert.
Stankevich shares a similar sentiment. "Unfortunately, the situation in 2026 illustrated that the retail fuel market has evolved chaotically over many years. We lack a qualified understanding of the adequate number of PS required to confidently assert the availability of infrastructure for consumers. Systematic planning for the development of the retail network is not currently taking place, resulting in many municipalities, even in Central Russia, lacking operational stations. In contrast, for electricity and heating supply facilities, such planning is undertaken at the government level through regularly updated documentation (placement schemes). The situation in fuel retail also needs corrective measures," he stated.
Source: RG.RU